Business
മൊബൈൽ നമ്പർ പോലെ നിങ്ങളുടെ ബാങ്ക് അക്കൗണ്ടും ഇനി പോർട്ട് ചെയ്യാം: റിസർവ് ബാങ്ക്

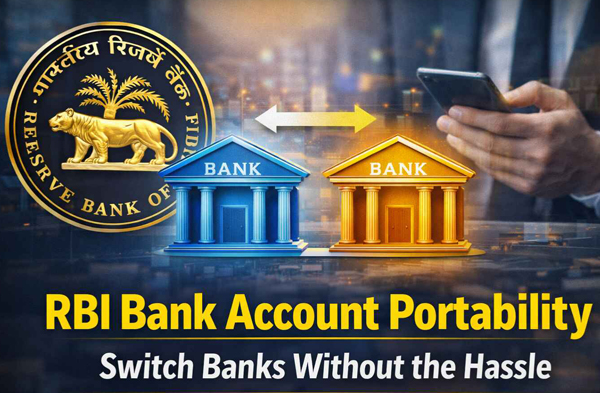
സാമ്പത്തിക ലോകത്തെ ഏറ്റവും വലിയ വിപ്ലവത്തിന് തുടക്കം കുറിച്ച് റിസർവ് ബാങ്ക്. ഉപഭോക്താക്കൾക്ക് തങ്ങളുടെ ബാങ്ക് സേവനങ്ങളിൽ സംതൃപ്തിയില്ലെങ്കിൽ മൊബൈൽ സിം കാർഡുകൾ മാറ്റുന്നതുപോലെ ലളിതമായി ബാങ്ക് മാറ്റാൻ സാധിക്കുന്ന ‘ബാങ്ക് അക്കൗണ്ട് പോർട്ടബിലിറ്റി’ എന്ന സംവിധാനം ഉടൻ യാഥാർത്ഥ്യമാകും.
റിസർവ് ബാങ്ക് തങ്ങളുടെ ‘പേയ്മെന്റ് വിഷൻ 2028’ എന്ന പദ്ധതിയുടെ ഭാഗമായി അവതരിപ്പിക്കുന്ന ഏറ്റവും പുതിയ പരിഷ്കരണമാണ് ബാങ്ക് അക്കൗണ്ട് പോർട്ടബിലിറ്റി. നിലവിൽ ഒരു ഉപഭോക്താവ് തന്റെ ബാങ്ക് മാറ്റാൻ ആഗ്രഹിച്ചാൽ നിലവിലുള്ള അക്കൗണ്ട് ക്ലോസ് ചെയ്യുകയും പുതിയ ബാങ്കിൽ പുതിയൊരു നമ്പർ ഉപയോഗിച്ച് അക്കൗണ്ട് തുടങ്ങുകയും വേണം. ഇത് വലിയ രീതിയിലുള്ള ബുദ്ധിമുട്ടുകൾ ഉണ്ടാക്കാറുണ്ട്. എന്നാൽ പുതിയ സംവിധാനം വരുന്നതോടെ ഒരു ബാങ്കിന്റെ സേവനങ്ങളിൽ തൃപ്തിയില്ലാത്തവർക്ക് അവരുടെ നിലവിലുള്ള അക്കൗണ്ട് നമ്പർ മാറ്റാതെ തന്നെ മറ്റൊരു ബാങ്കിന്റെ ഉപഭോക്താവായി മാറാൻ സാധിക്കും. ബാങ്കിംഗ് മേഖലയിൽ വലിയ മത്സരത്തിനും ഇത് വഴിതെളിക്കും.
ബാങ്ക് മാറുന്നതിലൂടെ ഉപഭോക്താക്കൾ നേരിടുന്ന ഏറ്റവും വലിയ പ്രതിസന്ധി അവരുടെ ഇഎംഐകൾ, ഇൻഷുറൻസ് പ്രീമിയങ്ങൾ, സിസ്റ്റമാറ്റിക് ഇൻവെസ്റ്റ്മെന്റ് പ്ലാനുകൾ (SIP) എന്നിവ പുനഃക്രമീകരിക്കുക എന്നതാണ്. അക്കൗണ്ട് പോർട്ടബിലിറ്റി വരുന്നതോടെ ഇത്തരം എല്ലാ ഓട്ടോമാറ്റിക് പേയ്മെന്റുകളും തടസ്സമില്ലാതെ പുതിയ ബാങ്കിലേക്ക് കൈമാറ്റം ചെയ്യപ്പെടും. ഓരോ തവണയും ശമ്പളം വരുന്ന അക്കൗണ്ട് നമ്പർ മാറ്റുന്നതിനായി ഓഫീസുകളിൽ അപേക്ഷ നൽകേണ്ടി വരില്ല. ഇത് സാധാരണക്കാരായ ഉപഭോക്താക്കൾക്ക് നൽകുന്ന ആശ്വാസം വളരെ വലുതാണ്. ബാങ്കുകൾ തമ്മിലുള്ള സേവനത്തിന്റെ നിലവാരം ഉയർത്താൻ ഈ മത്സരം കാരണമാകും.
ഈ സംവിധാനം നടപ്പിലാക്കുന്നതിനായി റിസർവ് ബാങ്ക് ‘പേയ്മെന്റ് സ്വിച്ചിംഗ് സർവീസ്’ (PaSS) എന്ന പുതിയ പ്ലാറ്റ്ഫോം വികസിപ്പിച്ചുവരികയാണ്. ഒരു ഉപഭോക്താവിന്റെ ബാങ്കിംഗ് വിവരങ്ങളും സ്ഥിരമായി നടക്കുന്ന പേയ്മെന്റുകളും ഈ സിസ്റ്റത്തിൽ സുരക്ഷിതമായി സൂക്ഷിക്കും. ഒരു ബാങ്കിൽ നിന്ന് മറ്റൊന്നിലേക്ക് പോർട്ട് ചെയ്യുമ്പോൾ ഈ പ്ലാറ്റ്ഫോം വഴി ഡാറ്റ കൈമാറാൻ സാധിക്കും. ബാങ്ക് മാറുമ്പോൾ ഐഎഫ്എസ്സി കോഡുകളിൽ മാറ്റം വന്നേക്കാമെങ്കിലും അക്കൗണ്ട് നമ്പർ മാറാത്തത് ഉപഭോക്താക്കളെ സംബന്ധിച്ച് വലിയ നേട്ടമാണ്. ഡിജിറ്റൽ ഇന്ത്യയുടെ കരുത്ത് വർദ്ധിപ്പിക്കുന്ന ഒന്നായിരിക്കും ഈ സാങ്കേതിക സംവിധാനം.
പലപ്പോഴും ബാങ്കുകൾ അമിതമായ സർവീസ് ചാർജുകൾ ഈടാക്കുന്നതും മോശം ഉപഭോക്തൃ സേവനം നൽകുന്നതും ഉപഭോക്താക്കളെ വലയ്ക്കാറുണ്ട്. എന്നാൽ അക്കൗണ്ട് മാറുന്നതിലെ ബുദ്ധിമുട്ട് ഭയന്ന് പലരും അതേ ബാങ്കിൽ തന്നെ തുടരുകയാണ് ചെയ്യുന്നത്. അക്കൗണ്ട് പോർട്ടബിലിറ്റി വരുന്നതോടെ ഉപഭോക്താവിന് തന്റെ ബാങ്കിനെ തിരഞ്ഞെടുക്കാനുള്ള പൂർണ സ്വാതന്ത്ര്യം ലഭിക്കും. സേവനം മോശമായാൽ ഉടൻ തന്നെ മികച്ച ബാങ്കിലേക്ക് മാറാം എന്ന സാഹചര്യം ബാങ്കുകളെ കൂടുതൽ ഉത്തരവാദിത്തമുള്ളവരാക്കി മാറ്റും. ഇത് ബാങ്കിംഗ് മേഖലയിൽ സുതാര്യതയും കൃത്യതയും ഉറപ്പുവരുത്താൻ സഹായിക്കും.
ബാങ്ക് അക്കൗണ്ട് പോർട്ടബിലിറ്റി നടപ്പിലാക്കുമ്പോൾ ഉപഭോക്താക്കളുടെ വിവരങ്ങളുടെ സുരക്ഷ ഉറപ്പാക്കാൻ റിസർവ് ബാങ്ക് കർശനമായ നിർദ്ദേശങ്ങളാണ് നൽകിയിട്ടുള്ളത്. സൈബർ ആക്രമണങ്ങളിൽ നിന്നും ഡാറ്റ ചോർച്ചയിൽ നിന്നും സംരക്ഷണം നൽകുന്നതിനായി എൻഡ്-ടു-എൻഡ് എൻക്രിപ്ഷൻ സാങ്കേതികവിദ്യയാണ് ഉപയോഗിക്കുന്നത്. ഉപഭോക്താവിന്റെ ക്രെഡിറ്റ് ഹിസ്റ്ററിയും ലോൺ വിവരങ്ങളും പോർട്ടിംഗ് സമയത്ത് കൃത്യമായി പുതിയ ബാങ്കിലേക്ക് മാറ്റപ്പെടും. ഇത് ബാങ്കുകൾ തമ്മിലുള്ള വിവര കൈമാറ്റം സുഗമമാക്കാനും വായ്പകൾ എടുക്കുന്നവർക്ക് കൂടുതൽ വേഗത്തിൽ സേവനങ്ങൾ ലഭ്യമാക്കാനും സഹായിക്കും.
Sources:azchavattomonline.com
Think about what’s tied to your current bank account. Salary credits. EMI deductions. SIP mandates. Utility bill auto-payments. Netflix, LIC, insurance premiums — all sitting quietly in the background, routing through the same account month after month.
Now imagine a competing bank offers you better interest rates, lower charges, or a genuinely superior app. Can you move? Technically yes. Practically, no — not without weeks of manually updating every single payment instruction. That friction is exactly what the Reserve Bank of India is now working to eliminate.
The RBI has placed bank account portability at the centre of its Payments Vision 2028, with plans to introduce a system that lets customers shift banks without losing their standing payment instructions. According to a Times of India report, the mechanism being developed is called the Payments Switching Service — and it could fundamentally change how Indians relate to their banks.
Why Bank Accounts in India Are Hard to Switch
Savings accounts in India are what banking professionals call “sticky.” Not because customers love their bank, but because leaving is genuinely painful.
Salary accounts are linked to employer payroll systems. Home loan EMIs are tied to auto-debit mandates. Insurance premiums, SIPs, credit card bill payments, subscriptions — each one is an instruction embedded in a specific account. Moving to another bank doesn’t just mean opening a new account. It means tracking down every single active mandate and updating it individually, often with multiple institutions, forms, and waiting periods involved.
Most customers don’t bother. And banks know this. That’s the stickiness — not loyalty, just inertia born from complexity.
RBI Payments Switching Service Explained: How Bank Account Portability Will Work
The RBI’s proposed fix is a centralised interface — referred to as the Payments Switching Service — that would sit above individual banks and consolidate all of a customer’s payment mandates in one place.
Through this interface, a customer would be able to view all their incoming and outgoing payment instructions across accounts and migrate them in bulk to a new bank. The entire process of switching, which currently takes weeks of manual coordination, could be handled through a single platform.
This is the banking equivalent of mobile number portability. When telecom regulators introduced number portability, customers could switch carriers without changing their phone number. The RBI is applying the same logic to bank accounts — your financial identity doesn’t have to be locked to one institution.
RBI Payments Vision 2028: Future of Digital Payments and Banking in India
RBI’s Payments Vision 2028 goes well beyond account portability. It reflects a broader strategic shift — placing consumer empowerment and reduced friction at the centre of how India’s payment ecosystem develops over the next few years.
The account portability initiative is one piece. Another is the push to make cross-border payments faster, cheaper, and more accessible — an area where India, like most countries, still has significant gaps. International transfers remain slow, expensive, and opaque compared to domestic UPI transactions, and the RBI has committed to a comprehensive review of the regulatory, operational, and technological bottlenecks involved.
That review is explicitly aimed at aligning India’s domestic systems with global standards shaped by the G20’s cross-border payments roadmap. India has already linked its fast payment infrastructure with several countries through bilateral agreements, and the Vision 2028 plan accelerates that work.
The broader framework also includes continued development of India’s central bank digital currency (CBDC), with a focus on expanding its acceptance and functionality as part of the payment ecosystem rather than treating it as a separate track.
Cross-Border Payments in India: Challenges and RBI’s 2028 Solution Plan
Sending money abroad from an Indian bank account is, to put it plainly, still a frustrating experience. Transactions take one to five business days. Fees can be substantial. Exchange rate transparency varies. And the compliance requirements — FEMA declarations, purpose codes, documentation — add friction that discourages even legitimate transactions.
The RBI’s cross-border review under Payments Vision 2028 acknowledges this directly. The plan isn’t to bypass regulatory requirements — those exist for legitimate reasons — but to remove unnecessary operational friction and modernise the infrastructure that currently slows things down.
UPI’s international expansion is part of this. Its linkage with Singapore’s PayNow, the UAE’s payment network, and several other systems has already shown what’s possible when domestic fast payment rails are extended across borders. Vision 2028 looks to widen and deepen those connections.
What RBI’s Bank Account Portability Means for Customers Today
Practically speaking, nothing changes today. The Payments Vision 2028 is a framework — a direction the RBI has set — not a product that’s live.
Honestly, a firm timeline for when the Payments Switching Service will be available to consumers hasn’t been confirmed yet. The RBI has signalled intent, but the actual rollout will depend on regulatory groundwork, bank system integration, and the kind of testing that takes time.
What’s worth noting is that the problem being targeted is real. Millions of Indian bank customers are effectively locked into accounts they’d move away from if switching weren’t so cumbersome. The RBI has named that problem explicitly — that’s not nothing. Regulatory acknowledgement of a friction point is usually the first step before anything actually gets built.
Bank Account Portability FAQs: Everything You Need to Know
How do I switch banks in India without losing all my auto-payments?
Right now, there’s no easy way — and that’s precisely the problem the RBI is trying to address. Currently, switching your primary bank account means manually contacting each institution that holds an auto-debit mandate against your account: your employer for salary, your lender for EMI, your insurer, your mutual fund platform, and so on. Each has its own process and timeline. The proposed Payments Switching Service would centralise all of this into a single interface, letting you migrate mandates in bulk. Until that system is live, the most practical approach is to maintain your old account active during a transition period while gradually shifting mandates to the new one — typically over two to three months.
What is the RBI Payments Switching Service and when will it launch?
The Payments Switching Service is a centralised platform the RBI intends to build as part of its Payments Vision 2028 plan. It would allow bank customers to view all active payment mandates — incoming and outgoing — and transfer them to a different bank without manual intervention at each institution. No official launch date has been announced. The RBI has committed to a review of the regulatory and technological requirements, but implementation timelines for infrastructure of this scale in India typically run two to four years from policy announcement to consumer availability. Keep an eye on RBI circulars and annual payment system reports for concrete updates.
Why is it so difficult to change my salary account even when a better bank is available?
Salary accounts are particularly sticky because the link isn’t just between you and your bank — it’s between your employer’s payroll system and your bank. Your employer’s HR or finance team has to initiate a change at their end, which involves internal approvals and sometimes technical integrations. On top of that, any linked mandates — credit card autopay, loan EMIs, SIPs — each require separate updates with separate institutions. The RBI has explicitly called this “stickiness” a problem worth solving. The Payments Switching Service is specifically designed to decouple your payment identity from any single bank, though it won’t necessarily change the employer-side payroll link on its own.
Will RBI bank account portability work exactly like mobile number portability?
The analogy is useful but not perfect. Mobile number portability lets you keep the same number while switching carriers — a clean, single identifier that follows you. Bank account portability is more complex because there are many more attached instructions: dozens of payment mandates tied to dozens of institutions, each with their own systems. The RBI’s approach isn’t to give you a portable account number (at least not as currently described) — it’s to make it easy to migrate all your standing instructions to a new account number at a different bank. The outcome is similar: you can switch without losing your financial continuity. The mechanics underneath are different. Practical tip: think of it less like number portability and more like forwarding all your mail when you move house — same result, different process.
Can I keep my existing account number if I switch banks under this new plan?
Based on what’s been announced, the RBI’s plan doesn’t involve transferring your existing account number to a new bank. Account numbers are bank-specific identifiers, and changing that would require a much deeper restructuring of banking infrastructure. What the Payments Switching Service would allow is migrating your payment mandates — the instructions to send and receive money — to a new account at a different bank. Your old account number stays with your old bank, but your financial life moves with you. The distinction matters practically: anyone who has your current account number saved for transfers (family, clients, employers) would need to be updated with your new details.
How RBI Is Transforming India’s Payment Ecosystem for the Future
The account portability proposal sits inside something larger. India spent the last decade building payment infrastructure — UPI, IMPS, NACH, FASTag, now CBDC — and those systems have genuinely transformed how money moves domestically.
What Vision 2028 signals is that the next phase isn’t just about adding new rails. It’s about reducing the friction that still exists for users navigating those rails — switching banks, sending money abroad, managing multiple mandates across institutions, understanding what’s happening to their money in real time.
The RBI is essentially asking: now that we’ve built this, are customers actually free to use it on their own terms? Account portability is one answer to that question. The cross-border payments review is another. The CBDC expansion is a third.
None of it arrives overnight. But the direction is clear — and for most Indian bank customers, it’s a direction worth watching
http://theendtimeradio.com






Business
പിഎഫ് പിൻവലിക്കൽ ചട്ടങ്ങളിൽ വൻ മാറ്റം; ഇനി 90% വരെ പിൻവലിക്കാം, വിരമിച്ചവർക്ക് മാസവരുമാനവും
പിഎഫ് അക്കൗണ്ടിലെ സമ്പാദ്യം ആവശ്യങ്ങൾക്കനുസരിച്ച് ഉപയോഗിക്കാൻ ജീവനക്കാർക്ക് കൂടുതൽ വഴികൾ തുറക്കുകയാണ് ഇപിഎഫ്ഒ. അക്കൗണ്ടിൽനിന്ന് പണം പിൻവലിക്കാനുള്ള പരിധി ഉയർത്തുന്നതിനൊപ്പം വിരമിച്ച ശേഷവും പിഎഫ് സമ്പാദ്യം വരുമാനമാക്കി മാറ്റാൻ സഹായിക്കുന്ന പുതിയ സംവിധാനത്തിനും അംഗീകാരം ലഭിച്ചു. 55 വയസിന് താഴെയുള്ളവർക്ക് അക്കൗണ്ടിലെ തുകയുടെ 90 % വരെ പിൻവലിക്കാം. വിരമിച്ചവർക്ക് മുഴുവൻ സമ്പാദ്യവും ഒരുമിച്ച് പിൻവലിക്കാതെ തവണകളായി കൈപ്പറ്റാനും ഇനി അവസരമുണ്ടാകും. ഇന്ന് ചേർന്ന ഇപിഎഫ്ഒ കേന്ദ്ര ട്രസ്റ്റി ബോർഡ് യോഗത്തിലാണ് ഈ തീരുമാനങ്ങൾ കൈക്കൊണ്ടത്.
നിലവിൽ ജീവനക്കാർ വിരമിക്കുമ്പോൾ പിഎഫ് അക്കൗണ്ടിലെ മുഴുവൻ തുകയും പിൻവലിക്കുന്നതാണ് പതിവ്. എന്നാൽ വലിയൊരു തുക ഒരുമിച്ച് ലഭിക്കുമ്പോൾ അത് എവിടെ നിക്ഷേപിക്കണം, എങ്ങനെ സ്ഥിരവരുമാനമാക്കി മാറ്റണം തുടങ്ങിയ ആശങ്കകൾ പലരെയും അലട്ടാറുണ്ട്. ഈ പ്രശ്നത്തിന് പരിഹാരമാകുന്നതാണ് പുതിയ സിസ്റ്റമാറ്റിക് വിഡ്രോവൽ പ്ലാൻ (എസ്ഡബ്ല്യുപി). വിരമിച്ചവർക്ക് പിഎഫ് സമ്പാദ്യത്തിന്റെ ഒരു ഭാഗം അക്കൗണ്ടിൽത്തന്നെ നിലനിർത്തി ബാക്കി തുക ആവശ്യാനുസരണം പിൻവലിക്കാം. അക്കൗണ്ടിൽ ശേഷിക്കുന്ന തുകയ്ക്ക് ഇപിഎഫ്ഒ നിശ്ചയിക്കുന്ന നിരക്കിൽ പലിശയും ലഭിക്കും.
ഉദാഹരണത്തിന്, ഒരാളുടെ പിഎഫ് സമ്പാദ്യം 50 ലക്ഷം രൂപയാണെന്ന് കരുതുക. ഇതിൽ 20 ലക്ഷം രൂപ പിൻവലിച്ച് ബാക്കി 30 ലക്ഷം രൂപ അക്കൗണ്ടിൽ നിലനിർത്താം. ശേഷിക്കുന്ന തുകയിൽനിന്ന് നിശ്ചിത ഇടവേളകളിൽ ഒരു നിശ്ചിത തുക വീതം പിൻവലിച്ച് വരുമാനമായി ഉപയോഗിക്കാം. അല്ലെങ്കിൽ 30 ലക്ഷം രൂപയ്ക്ക് ലഭിക്കുന്ന പലിശ മാത്രം പിൻവലിക്കാനും സൗകര്യമുണ്ടാകും.
എസ്ഡബ്ല്യുപി സംവിധാനത്തിൽ ചേർന്ന ശേഷം ആവശ്യമെങ്കിൽ പദ്ധതി അവസാനിപ്പിച്ച് അക്കൗണ്ടിലുള്ള ബാക്കി തുക മുഴുവനായി പിൻവലിക്കാനും കഴിയും. ഈ കാലയളവിൽ വരിക്കാരൻ മരിച്ചാൽ നോമിനിക്കോ ആശ്രിതർക്കോ ശേഷിക്കുന്ന തുക ഒറ്റത്തവണയായി കൈപ്പറ്റാം. അല്ലെങ്കിൽ തവണകളായി പിൻവലിക്കുന്നത് തുടരാനും അവസരമുണ്ടാകും.
55 വയസിന് മുമ്പ് 90 % വരെ പിൻവലിക്കാം
പിഎഫ് അക്കൗണ്ടിൽനിന്ന് 90 % വരെ തുക പിൻവലിക്കാനുള്ള സൗകര്യവും പുതിയ മാറ്റത്തിന്റെ ഭാഗമാണ്. 55 വയസ് വരെയാണ് ഈ ആനുകൂല്യം ലഭിക്കുക. വരിക്കാരന്റെയോ കുടുംബാംഗങ്ങളുടെയോ ചികിത്സ, വിദ്യാഭ്യാസം, വിവാഹം തുടങ്ങിയ ആവശ്യങ്ങൾക്ക് പണം പിൻവലിക്കാം. വീട്, ഭൂമി എന്നിവ വാങ്ങുന്നതിനും വീട് നിർമിക്കുന്നതിനും ഭവനവായ്പ തിരിച്ചടയ്ക്കുന്നതിനും വീടിന്റെ അറ്റകുറ്റപ്പണികൾക്കുമായി തുക ഉപയോഗിക്കാനും അനുമതിയുണ്ട്. ചില പ്രത്യേക സാഹചര്യങ്ങളിലും പിൻവലിക്കൽ അനുവദിക്കും.
ജോലി നഷ്ടപ്പെട്ടവർക്ക് പിഎഫ് തുക പിൻവലിക്കുന്നതിനുള്ള സമയപരിധിയിലും മാറ്റമുണ്ട്. ജോലി നഷ്ടപ്പെട്ട് 12 മാസം കാത്തിരിക്കണമെന്ന നിലവിലെ നിബന്ധനയ്ക്ക് പകരം, ഇനി രണ്ട് മാസത്തിനുള്ളിൽ തന്നെ ഇപിഎഫ് തുക പിൻവലിക്കാൻ സാധിക്കും.
പിഎഫ് സമ്പാദ്യം ഇനി വിരമിക്കൽ കാലത്തേക്കുള്ള ഒറ്റത്തവണത്തുകയായി മാത്രം കാണേണ്ടതില്ലെന്നതാണ് പുതിയ മാറ്റങ്ങളുടെ പ്രത്യേകത. ആവശ്യങ്ങൾക്കായി കൂടുതൽ തുക പിൻവലിക്കാനും ശേഷിക്കുന്ന സമ്പാദ്യം വരുമാനമായി ഉപയോഗിക്കാനും ഇതിലൂടെ അവസരം ലഭിക്കും. ജോലി നഷ്ടപ്പെടുന്ന സാഹചര്യത്തിലും പണം കൈപ്പറ്റാനുള്ള കാത്തിരിപ്പ് കുറയും. പുതിയ വ്യവസ്ഥകൾ പ്രാബല്യത്തിൽ വരുന്നതോടെ പിഎഫ് അംഗങ്ങൾക്ക് അവരുടെ സമ്പാദ്യം കൂടുതൽ സൗകര്യപ്രദമായി വിനിയോഗിക്കാനാകും.
Sources:mediamangalam
In a decision that can benefit crores of subscribers, the Employees’ Provident Fund Organisation (EPFO) has approved a proposal to reduce the minimum EPF balance requirement from 25% to 10% for members up to 55 years of age.
Following this change, these EPF members will be allowed to withdraw up to 90% of their corpus. The earlier withdrawal limit of the EPF corpus for the same age group was up to 90% of their corpus. The earlier withdrawal limit of the EPF corpus for the same age group was up to 75%. The eligibility to withdraw all 100% corpus at retirement, however, remains the same.
At its Central Board of Trustees (CBT) meeting today (Thursday, November 19, 2026), the EPFO has also cut the EPF withdrawal waiting period after job loss from 12 months to 2 months.
Other than that, the EPFO has also approved the Systematic Withdrawal Plan (SWP) for Employees’ Provident Fund (EPF) withdrawal on retirement.
The CBT also gave in-principle approval to allow investment of up to 3% of fresh accretion in eligible Alternative Investment Funds. It has approved amendments to EDLI Scheme, 2026, to facilitate resolution of pending legacy exemption cases and provide a six-month window to eligible establishments for renewal of expired exemptions. Proposals concerning surrender of exemption by 27 establishments and cancellation of exemption in four establishments were reviewed.
However, the EPFO didn’t announce any increase in the Employees’ Pension Scheme (EPS). It also didn’t take any decision on whether it will approve higher EPS pension cases of all applicants.
EPF members up to 55 years of age need to maintain 10% EPF balance now
EPF subscribers now need to maintain a minimum of 10% of their EPF corpus till 55 years of age. Earlier, 25% of the EPF contribution needed to be retained.
The full withdrawal of the entire PF balance (including the minimum balance) is allowed in case of retirement after attaining 55 years of age, permanent disability, inability to work, retrenchment, voluntary retirement or leaving India permanently, among others.
Sandeep Sehgal, partner-tax & valuations, AKM Global, said the EPFO board’s proposal to cut the minimum balance for partial withdrawals from 25% to 10% would give employees more flexibility to manage their finances, so that they can meet urgent expenses without resorting to high-cost borrowing.
“Once notified, the change would allow eligible members to withdraw up to 90% of their eligible PF balance, subject to the applicable conditions,” says Sehgal.
EPF withdrawal period after job loss cut
The EPFO has also reversed its earlier decision of cutting the time from 12 months to 2 in case of job loss.
According to the earlier rule, in case of unemployment, 75% PF balance (that includes employer and employee contribution and interest earned) could be withdrawn immediately. The remaining 25% could also be withdrawn after one year.
A full withdrawal of the entire PF balance (including the minimum balance of 25%) was allowed for those retiring after attaining 55 years of age.
SWP option for EPF withdrawals
The CBT in its meeting today approved a proposal to introduce a Systematic Withdrawal Plan (SWP) for EPF withdrawals. The option will enable retiring EPF members to receive their accumulated provident fund savings in periodic instalments instead of withdrawing the entire amount in one go.
The Ministry of Labour & Employment said in a statement, “This reform will enable retiring members to withdraw their accumulated provident fund savings at regular intervals, such as monthly, quarterly or half-yearly, based on their preference. This facility would provide members with a structured source of periodic income while allowing the remaining corpus to continue generating returns.”
The introduction of SWP will enable members to convert their retirement savings into a stable and predictable stream of systematic withdrawals post-retirement, while preserving the ownership of the underlying corpus.
The EPFO says that in case of the member’s death during the payout period, the nominee or dependent will be ableto withdraw the remaining balance or continue receiving periodic payments.
Earlier, the SWP option was available to NPS subscribers. But now, EPF subscribers can also enjoy the facility.
Relief in EDLI exemption cases
The CBT has also approved amendments to EDLI Scheme, 2026, to facilitate resolution of pending legacy exemption cases. It has provided a six-month window to eligible establishments for renewal of expired exemptions, along with relief from contributions, interest and penal damages for the verified transitional period.
“This will provide relief to eligible establishments by facilitating the settlement of pending and expired exemption cases, with a six-month window for renewal and relaxation from contributions, interest and penal damages for the verified transitional period,” the Labout Ministry says.
http://theendtimeradio.com
കൊച്ചി: മുതിർന്ന പൗരന്മാരുടെ സ്ഥിരനിക്ഷേപങ്ങൾക്കുള്ള അധിക പലിശനിരക്കിൽ വർദ്ധനവ് വരുത്തി ഫെഡറൽ ബാങ്ക്. നിലവിൽ ലഭിക്കുന്ന 0.50 ശതമാനത്തിനു പകരം 0.60 ശതമാനം പലിശയാണ് സ്ഥിരനിക്ഷേപങ്ങൾക്ക് ഇനി മുതൽ അധികമായി ലഭിക്കുക. ഇതോടെ മുതിർന്ന പൗരന്മാർക്കുള്ള സ്ഥിര നിക്ഷേപ പലിശനിരക്ക് 7.50 ശതമാനം വരെയായി ഉയർന്നു. 18 മാസം, രണ്ട് വർഷം മുതൽ മൂന്ന് വർഷത്തിൽ താഴെയുമുള്ള കാലാവധികളിലെ സ്ഥിരനിക്ഷേപങ്ങളുടെ പലിശനിരക്കും വർധിപ്പിച്ചിട്ടുണ്ട്.
കാലാവധിക്ക് മുൻപ് പിൻവലിക്കാൻ സൗകര്യമുള്ള നിക്ഷേപങ്ങൾക്ക് മേൽപ്പറഞ്ഞ കാലയളവിൽ 7.40 ശതമാനം പലിശ ലഭിക്കും. ഇതേ കാലയളവിൽ, ഒരു കോടി രൂപയിൽ കൂടുതലുള്ള, കാലാവധിക്ക് മുൻപ് പിൻവലിക്കാൻ സൗകര്യമില്ലാത്ത നിക്ഷേപങ്ങൾക്ക് 7.50 ശതമാനം പലിശ ലഭിക്കും. 35 മാസത്തേക്കുള്ള ഇത്തരം നിക്ഷേപങ്ങളുടെ ഫലപ്രദ വാർഷിക ആദായം യഥാക്രമം 8.18 ശതമാനവും 8.30 ശതമാനവുമാണ്. ഈ കാലാവധിയിലുള്ള സ്ഥിര നിക്ഷേപ പദ്ധതികൾക്ക് മുതിർന്ന പൗരന്മാർ അല്ലാത്ത പൊതുജനങ്ങൾക്കും (എൻആർഇ/എൻആർഒ നിക്ഷേപങ്ങൾ ഉൾപ്പെടെ) യഥാക്രമം 6.80 ശതമാനവും 6.90 ശതമാനവും വാർഷിക പലിശ ലഭ്യമാണ്.
പുതുക്കിയ നിരക്കുകൾ നവംബർ 12 മുതൽ പ്രാബല്യത്തിലായി. ₹3 കോടിയിൽ താഴെയുള്ള ഒറ്റത്തവണ സ്ഥിര നിക്ഷേപങ്ങൾക്കാണ് ഈ നിരക്കുകൾ ബാധകം.
ഇടപാടുകാർക്ക്, പ്രത്യേകിച്ച് സുരക്ഷിതവും മികച്ച ആദായം നൽകുന്നതുമായ സ്ഥിരനിക്ഷേപ അവസരങ്ങൾ തേടുന്ന മുതിർന്ന പൗരന്മാർക്ക്, കൂടുതൽ മൂല്യം നൽകാനുള്ള ബാങ്കിന്റെ പ്രതിബദ്ധതയാണ് പുതുക്കിയ പലിശ നിരക്കുകൾ വ്യക്തമാക്കുന്നതെന്ന് ബാങ്കിന്റെ എക്സിക്യുട്ടീവ് വൈസ് പ്രസിഡന്റും റീട്ടെയ്ൽ ലയബിലിറ്റി & ഫീ പ്രോഡക്ട് കൺട്രി ഹെഡുമായ ജോയ് പി വി പറഞ്ഞു. ഉറപ്പുള്ള ആദായവും കാലാവധിക്കു മുമ്പ് പണം പിൻവലിക്കാനുള്ള സൗകര്യവും ഒരുപോലെ ലഭിക്കുന്നതിനാൽ, സുരക്ഷയും പണലഭ്യതയും മികച്ച വരുമാനവും ആഗ്രഹിക്കുന്നവർക്ക് ഈ നിക്ഷേപങ്ങൾ മികച്ച സമ്പാദ്യ മാർഗമാണെന്നും അദ്ദേഹം കൂട്ടിച്ചേർത്തു.
ഫെഡറൽ ബാങ്ക് ശാഖകളിൽ നിന്ന് നേരിട്ടും ഡിജിറ്റൽ സൗകര്യങ്ങൾ മുഖേനയും ഇടപടുകാർക്ക് സ്ഥിരനിക്ഷേപം തുടങ്ങാം.
Sources:expressherald
Federal Bank has increased the additional interest rate benefit offered to senior citizens on term deposits from 0.50% to 0.60%. Following the revision, senior citizens can earn up to 7.50% per annum on select fixed deposit (FD) tenures.
The revised interest rates came into effect on November 12, 2026. The change applies to deposit tenures of 18 months and two years to less than three years. The revised rates are applicable to single term deposits below ₹3 crore.
For deposits with a premature withdrawal facility, senior citizens can earn up to 7.40% per annum. The rate goes up to 7.50% for deposits of ₹1 crore and above without a premature withdrawal facility.
Here is a look at the revised Federal Bank FD rates for senior citizens and general depositors, along with the latest rates offered by other banks.
Federal Bank FD rates for senior citizens
Federal Bank is offering an interest rate of 7.40% per annum to senior citizens on term deposits with a premature withdrawal facility. For a 35-month deposit, this translates into an effective annualised yield of up to 8.18%, according to the bank.
For term deposits of ₹1 crore and above without a premature withdrawal facility, senior citizens can earn 7.50% per annum. The effective annualised yield can go up to 8.30% for a 35-month tenure.
The revised benefit follows the bank’s decision to increase the additional interest offered to senior citizens from 0.50% to 0.60%. The rates apply to the specified tenures and eligible deposits below ₹3 crore.
Federal Bank FD rates for general public
For the same deposit tenures, general customers, including non-resident Indians (NRIs), can earn 6.80% per annum on term deposits with a premature withdrawal facility.
For deposits without a premature withdrawal facility, the bank is offering an interest rate of 6.90% per annum.
The revised rates are effective from November 12, 2026, and apply to single term deposits below ₹3 crore.
Customers can book these term deposits through Federal Bank branches or the bank’s digital channels.
Which other banks have revised FD rates?
Several banks have revised their fixed deposit interest rates in recent weeks. Here is a look at the latest rates offered by some lenders to senior citizens and general depositors.
http://theendtimeradio.com
Business
വാട്സ്ആപ്പ് ചാറ്റിൽനിന്ന് നേരിട്ട് ഇൻസ്റ്റഗ്രാം റീൽസ് പങ്കിടാം; പുതിയ ബട്ടണുമായി മെറ്റ, വരുന്നത് കിടിലൻ ഫീച്ചർ!
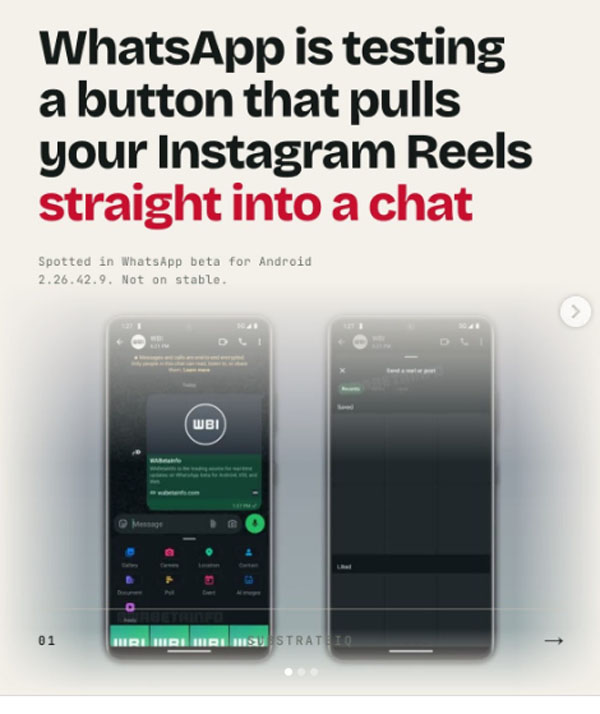
ഇൻസ്റ്റഗ്രാമിൽ കണ്ടിഷ്ടപ്പെട്ട റീൽസ് സുഹൃത്തുക്കൾക്ക് അയയ്ക്കാൻ ഇനി ആപ്പുകൾ മാറിമാറി ഉപയോഗിക്കേണ്ടിവരില്ല. റീൽസുകൾ കണ്ടെത്തുന്നതും പങ്കിടുന്നതും കൂടുതൽ ലളിതമാക്കുന്ന പുതിയ സംവിധാനവുമായി വാട്സ്ആപ്പ്. ചാറ്റിലെ അറ്റാച്ച്മെന്റ് മെനുവിൽ ഇൻസ്റ്റഗ്രാം റീൽസുകൾക്കായി പ്രത്യേക ബട്ടൺ ഉൾപ്പെടുത്തുന്ന ഫീച്ചറാണ് മെറ്റ പരീക്ഷിക്കുന്നത്. ഇതിലൂടെ ഇൻസ്റ്റഗ്രാമിൽ അടുത്തിടെ കണ്ടതും ലൈക്ക് ചെയ്തതും സേവ് ചെയ്തതുമായ റീൽസുകൾ വാട്സ്ആപ്പിൽനിന്നുതന്നെ കണ്ടെത്തി സുഹൃത്തുക്കൾക്ക് അയയ്ക്കാനാകും. തിരഞ്ഞെടുത്ത ആൻഡ്രോയിഡ് ബീറ്റാ ഉപയോക്താക്കൾക്ക് പുതിയ സൗകര്യം ലഭ്യമായിത്തുടങ്ങിയതായാണ് റിപ്പോർട്ട്.
വാട്സ്ആപ്പിലെ പുതിയ ഫീച്ചറുകളെക്കുറിച്ചുള്ള വിവരങ്ങൾ പുറത്തുവിടുന്ന ഡബ്ല്യുഎബീറ്റാഇൻഫോയുടെ റിപ്പോർട്ട് അനുസരിച്ച്, ആൻഡ്രോയിഡിനായുള്ള വാട്സ്ആപ്പ് ബീറ്റാ പതിപ്പായ 2.26.42.9 ലാണ് ഈ സംവിധാനം പരീക്ഷിക്കുന്നത്. ഗൂഗിൾ പ്ലേ സ്റ്റോർ വഴി ലഭിക്കുന്ന ബീറ്റാ പതിപ്പിലെ ചില ഉപയോക്താക്കൾക്കാണ് നിലവിൽ ഫീച്ചർ ലഭ്യമാക്കിയിരിക്കുന്നത്.
ചാറ്റിൽ പുതിയ റീൽസ് ബട്ടൺ; ഇഷ്ടപ്പെട്ട വിഡിയോകൾ ഒറ്റയിടത്ത്
പുതിയ സംവിധാനം ലഭിക്കുന്ന ഉപയോക്താക്കൾക്ക് വാട്സ്ആപ്പ് ചാറ്റിലെ അറ്റാച്ച്മെന്റ് മെനുവിൽ റീൽസിനായി പ്രത്യേക ബട്ടൺ കാണാനാകും. ഇതിൽ അമർത്തുന്നതോടെ ഇൻസ്റ്റഗ്രാമിലെ ഉപയോക്താവിന്റെ പ്രവർത്തനങ്ങളുമായി ബന്ധപ്പെട്ട റീൽസുകൾ ലഭ്യമാകും.
അടുത്തിടെ കണ്ട റീൽസുകൾ, സേവ് ചെയ്തവ, ലൈക്ക് ചെയ്തവ എന്നിങ്ങനെ വ്യത്യസ്ത ടാബുകളിലായിരിക്കും വിഡിയോകൾ ക്രമീകരിച്ചിരിക്കുന്നത്. അതിനാൽ മുമ്പ് കണ്ട ഒരു റീൽ വീണ്ടും കണ്ടെത്താനോ സേവ് ചെയ്തുവച്ച വിഡിയോ സുഹൃത്തിന് അയയ്ക്കാനോ ഇൻസ്റ്റഗ്രാമിലേക്ക് പ്രത്യേകം പോകേണ്ടതില്ല. ആവശ്യമായ റീൽ തിരഞ്ഞെടുത്ത് വാട്സ്ആപ്പ് ചാറ്റിലൂടെ നേരിട്ട് പങ്കിടാം.
ഫീച്ചർ ലഭിക്കാൻ അക്കൗണ്ടുകൾ ബന്ധിപ്പിക്കണം
എന്നാൽ പുതിയ സൗകര്യം ഉപയോഗിക്കുന്നതിന് ഒരു നിബന്ധനയുണ്ട്. വാട്സ്ആപ്പ് അക്കൗണ്ട് മെറ്റയുടെ അക്കൗണ്ട്സ് സെന്ററുമായി ബന്ധിപ്പിച്ചിരിക്കണം. ഇതുവഴിയാണ് ഇൻസ്റ്റഗ്രാമിലെ ഉപയോക്താവിന്റെ പ്രവർത്തനങ്ങളുമായി ബന്ധപ്പെട്ട റീൽസുകൾ വാട്സ്ആപ്പിൽ ലഭ്യമാകുന്നത്. മൊബൈൽആപ്പുകൾ കാണൂ
അതേസമയം, ഇൻസ്റ്റഗ്രാം, ഫേസ്ബുക്ക് അക്കൗണ്ടുകളുമായി വാട്സ്ആപ്പ് ബന്ധിപ്പിക്കാൻ താൽപര്യമില്ലാത്തവർക്ക് ആശങ്കപ്പെടേണ്ടതില്ല. അക്കൗണ്ടുകൾ ലിങ്ക് ചെയ്യുന്നത് നിർബന്ധമല്ല. നിലവിലുള്ള രീതിയിൽ ആപ്പുകൾ ഉപയോഗിക്കുന്നത് തുടരാം. എന്നാൽ അക്കൗണ്ടുകൾ ബന്ധിപ്പിക്കാത്തവർക്ക് അറ്റാച്ച്മെന്റ് മെനുവിലെ പുതിയ റീൽസ് ഷോർട്ട്കട്ട് ലഭിക്കില്ല.
റീൽസ് പങ്കിടാൻ ഇനി അധിക നടപടികൾ വേണ്ട
ഇൻസ്റ്റഗ്രാം, ഫേസ്ബുക്ക് എന്നിവയിലെ സ്റ്റോറികൾ, പോസ്റ്റുകൾ, റീൽസുകൾ തുടങ്ങിയവ വാട്സ്ആപ്പിലൂടെ പങ്കിടാനുള്ള സൗകര്യം നിലവിലുണ്ട്. എന്നാൽ ആവശ്യമായ ഉള്ളടക്കം കണ്ടെത്താൻ മീഡിയ പിക്കർ ഉൾപ്പെടെയുള്ള സംവിധാനങ്ങളെ ആശ്രയിക്കേണ്ടിവരുന്നു.
പുതിയ റീൽസ് ബട്ടൺ എത്തുന്നതോടെ ഈ നടപടികൾ കൂടുതൽ ലളിതമാകും. ഉപയോക്താക്കൾക്ക് ഇഷ്ടപ്പെട്ട റീൽസുകൾ വേഗത്തിൽ കണ്ടെത്താനും സംഭാഷണത്തിനിടെതന്നെ മറ്റുള്ളവരുമായി പങ്കുവയ്ക്കാനും കഴിയും. ഇൻസ്റ്റഗ്രാമും വാട്സ്ആപ്പും തമ്മിലുള്ള ഉള്ളടക്ക പങ്കിടൽ കൂടുതൽ സുഗമമാക്കുകയാണ് ഈ മാറ്റത്തിലൂടെ മെറ്റ ലക്ഷ്യമിടുന്നത്.
എല്ലാവർക്കും ഫീച്ചർ ലഭിക്കാൻ കാത്തിരിക്കണം
നിലവിൽ പരീക്ഷണഘട്ടത്തിലുള്ള ഫീച്ചർ തിരഞ്ഞെടുത്ത ആൻഡ്രോയിഡ് ബീറ്റാ ഉപയോക്താക്കൾക്ക് മാത്രമാണ് ലഭിക്കുന്നത്. വാട്സ്ആപ്പിന്റെ 2.26.42.9 ബീറ്റാ പതിപ്പ് ഇൻസ്റ്റാൾ ചെയ്തിട്ടുണ്ടെങ്കിലും എല്ലാവരുടെയും ഫോണിൽ പുതിയ റീൽസ് ബട്ടൺ പ്രത്യക്ഷപ്പെടണമെന്നില്ല. ഘട്ടംഘട്ടമായാണ് പരീക്ഷണം കൂടുതൽ ഉപയോക്താക്കളിലേക്ക് വ്യാപിപ്പിക്കുന്നത്. ജേണലിസംപഠിക്കാം
ഫീച്ചർ പൊതുഉപയോക്താക്കൾക്ക് എപ്പോൾ ലഭ്യമാകുമെന്ന കാര്യത്തിൽ വാട്സ്ആപ്പ് ഇതുവരെ ഔദ്യോഗിക പ്രഖ്യാപനം നടത്തിയിട്ടില്ല. പരീക്ഷണഘട്ടത്തിലെ പ്രവർത്തനക്ഷമതയും ഉപയോക്താക്കളുടെ പ്രതികരണവും വിലയിരുത്തിയ ശേഷമായിരിക്കും തുടർനടപടികൾ.പരീക്ഷണം വിജയകരമായി പൂർത്തിയായി ഫീച്ചർ വ്യാപകമായി ലഭ്യമാകുന്നതോടെ സമൂഹമാധ്യമങ്ങളിലെ വിഡിയോ പങ്കിടൽ കൂടുതൽ വേഗത്തിലും സൗകര്യപ്രദമായും മാറിയേക്കും.
Sources:mediamangalam
Meta-owned popular instant messaging app WhatsApp is making it easier for users to share Instagram Reels with friends and family. The platform is testing a new shortcut that will allow users to find and share Reels directly from the chat attachment menu. This means users will not have to go through multiple steps to find Instagram content while chatting on WhatsApp.
The new feature is currently rolling out to some Android beta testers. It was spotted in WhatsApp beta for Android version 2.26.42.9, available through the Google Play Store. However, the feature is not available to everyone at the moment, WABetaInfo reported.
Earlier, WhatsApp introduced a feature that allowed users to access their Instagram and Facebook media from within the app. Users who linked their accounts through Meta’s Accounts Center could view their Instagram and Facebook Stories, posts and Reels through WhatsApp’s media picker.
However, users had to open the media picker and select Instagram from the available options to find the content. With the new update, the Meta app is making this process simpler by adding a dedicated Reels button to the chat attachment menu.
When users tap this shortcut, WhatsApp opens a separate screen where they can browse Instagram content and select what they want to share in a conversation.
How The New WhatsApp Reels Shortcut Works
The new interface includes three tabs — Recents, Saved and Liked. These sections help users find Instagram Reels based on their activity on the platform, according to the report
The Recents tab shows Reels users have recently watched on Instagram. The Saved tab includes Reels they have saved, while the Liked tab shows content they have liked on Instagram.
Users can browse these sections, select a Reel and share it directly in a WhatsApp chat. The dedicated shortcut is expected to make the feature easier to find, especially for people who regularly share Instagram content with their contacts.
There is one important condition for using the new shortcut. Users must link their WhatsApp account to Meta’s Accounts Center to access the feature. Those who have not linked their accounts will not see the dedicated Reels button in the attachment menu.
However, linking accounts remains optional. Users who prefer to keep their WhatsApp account separate from Instagram and Facebook can continue using WhatsApp without connecting them.
http://theendtimeradio.com

‘People Are Burning Churches, Priests Are Being Murdered’: France Plagued by Anti-Christian Violence
PARIS – In France, political protesters took to the streets for the fifth weekend in a row. This country, which...

‘Completely Unscorched!’: Kathy Ireland Praises God After Husband’s Miracle Survival, Reveals Bible Survived Fire
Former supermodel and businesswoman Kathy Ireland is praising God for her husband Greg’s survival after the engine of his commercial...

‘God Is Good’: 11-Month-Old Baby Found in Miraculous Rescue After Being Buried Alive
For nearly 24 hours, an 11-month-old baby lay buried beneath the dirt in the South Carolina woods. Alone, helpless and...

നേതൃത്വ ശാക്തീകരണത്തിന്റെ ആഹ്വാനവുമായി പാസ്റ്റേഴ്സ് ആൻഡ് ലീഡേഴ്സ് ഫാമിലി സെമിനാർ സമാപിച്ചു
ഡാളസ് : ഡാളസ് സിറ്റിവൈഡ് ഫെല്ലോഷിപ്പിന്റെ (DCF) 2026-ലെ വാർഷിക പാസ്റ്റേഴ്സ് ആൻഡ് ലീഡേഴ്സ് ഫാമിലി സെമിനാർ നവംബർ 14 ശനിയാഴ്ച ഗ്രേസ് ക്രിസ്ത്യൻ അസംബ്ലിയിൽ നടന്നു....
യൂറോപ്പിൽ ക്രൈസ്തവർക്കു നേരെയുള്ള ആക്രമണങ്ങളിൽ 44 ശതമാനം വർധനവ്
വിയന്ന: മുന് വര്ഷങ്ങള്ക്ക് സമാനമായി യൂറോപ്യന് ഭൂഖണ്ഡത്തില് ക്രൈസ്തവര്ക്ക് നേരെ ആക്രമണങ്ങളില് വലിയ വര്ദ്ധനവ് ഉണ്ടായതായി പുതിയ റിപ്പോര്ട്ട്. വിയന്ന ആസ്ഥാനമായുള്ള “ഒബ്സർവേറ്ററി ഓൺ ഇന്റോളറൻസ് ആൻഡ്...

The Completion of Bible Translation Is Within Reach: Global Church Steps Up
Last spring, Oasis Network for Community Transformation facilitated workshops in Guinea-Bissau and the Central African Republic for the Deaf in...
-
 us news3 weeks ago
Millions Encouraged to Open Their Bibles for Global Bible Month
-

 us news5 months ago
Mike Winger deletes YouVersion app over ‘The Passion Translation’ controversy, urges others to ‘use caution’
-
 us news6 months ago
‘America Is Hungry’: Hundreds Born Again and Baptized as Jesus Tent Revival Sweeps the Nation
-

 Movie9 months ago
Hollywood Actor Jen Lilley Launching New Ministry After ‘Vision’ From Holy Spirit
-
 world news12 months ago
പാകിസ്ഥാനിൽ പാസ്റ്റർ കമ്രാൻ മൈക്കിൾ തന്റെ മകളുടെ മുന്നിൽ വെച്ച് ക്രൂരമായി കൊല്ലപ്പെട്ടു.
-

 Travel10 months ago
കേരളത്തിൽ നിന്ന് ഭൂട്ടാനിലേക്ക് എങ്ങനെ ട്രെയിനിൽ പോകാം; വിസ വേണ്ട, വോട്ടർ ഐഡി മതി; ടിക്കറ്റ് നിരക്കും വഴികളും
-

 Movie8 months ago
Worship Leader Brooke Ligertwood Shares Stunning Testimony of Answered Prayer From Ukraine
-
 Movie3 months ago
Keith Getty says Christians must ‘sing the Bible’ in the age of AI ahead of Sing! Conference